
THE em THESIS
/ 2026 — 2031everything motorcycling
em
The thought behind the ride.
A complete read of the market we are entering, the wedge we are using to enter it, and the financial architecture that turns a passionate community into a $76B opportunity.
10
Sections
5Y
Horizon
1,335
Cr GMV
Low Transparency
High Friction
Low Trust
High Fragmentation
Low Penetration
Motorcycling's commerce layer is fragmented across offline operators, fake products, opaque OEM pricing, and digital afterthoughts. We map the five friction points that keep riders from completing a trusted lifecycle purchase.

The friction between a rider and the ride.
No One Stop Shop(fragmentation)
no single platform to complete a full lifecycle of a product and/or experience purchase, as shown below as a flywheel
THE RIDER'S JOURNEY
& repeat
DM For Price Culture(friction)
motorcycle tour operators, moto-skill schools and moto-accommodation partners operate with a low-tech high friction method of DM for price on WhatsApp and a notebook.
ANATOMY OF THE FRICTION
- 1
rider wants to book
a tour, a class, a stay
- 2
DMs operator on WhatsApp
“dates? price? availability?”
- 3
operator checks a notebook
manual lookup, no system
- 4
hours or days pass
no SLA, no status
- 5
maybe a quote arrives
no compare, no checkout
Flooded With Fakes(trust)
motorcycle riding gear and aftermarket accessories are inherently 'low-trust' categories with fakes and low quality imports flooding the market.
THE TRUST GAP
what a rider finds when searching for a helmet
genuine + certified
verified seller, real warranty
grey market / replica
looks legit, often isn't
outright fakes
won't protect in a crash
Indicative market split based on category interviews.
The OEM Conundrum(transparency)
motorcycle OEM parts buying experience has no transparency, and the shops are usually located in a seedy part of town, leading to a poor buying experience.
PICK ANY TWO
today, a rider has to pick any two
genuine parts
real OEM, not a knock-off
fair, visible price
no haggling, no surprises
safe, reputable shop
not a back-alley counter
No Digital First Thinking(penetration)
most online moto-product websites are just a part of a 'channel' strategy of an offline store, limited in offering and lacking adequate product information.
OFFLINE-FIRST vs DIGITAL-FIRST
offline-first store vs digital-first store
Riding the
Premium Wave.
Premium motorcycles and weekend riders are the fastest-growing segments, creating a lifestyle economy that spends repeatedly. The data shows higher ASPs, natural repeat behaviour, and built-in community evangelism.
premium bikes
≥ 250cc, lifestyle segment
commuter bikes
entry-level, utility segment
a growing tribe
for whom motorcycling is a lifestyle, not a commute.
schools · tours · leagues
riding schools, moto-tour operators, made-for-OTT racing (e.g. ISRL).
premium basket
higher than average retail ticket size and order value.
repeat behaviour
multi-category play that supports customers' own motorcycle or lifestyle upgrades, retaining the customer within the em ecosystem
evangelise by default
riders publicly rate, review and recommend branded products.
the upgrade loop
multiple categories in riding-gear, parts and accessories, and wide appeal of motorcycling inspired fashion and accessories trigger high repeats.
$76Bn+ by 2035.
The TAM, global.
The global motorcycling commerce and experiences market is set to expand from ~$33.7B to ~$76.7B by 2031. Riding gear, accessories, and moto-tourism are the three engines of that growth.

THE INVESTED ENTHUSIAST
A premium tribe, riding into a $76B horizon.
Apparel & Protective Gear
Rapid shift toward premium, weather-resistant touring gear and smart/airbag wearables.
Aftermarket Accessories
High-intent purchasing of luggage systems, tech mounts, and performance parts during the '72-Hour Gap' post-bike purchase.
Moto-Tourism & Rentals
The fragmentation of independent tour guides consolidating into trusted digital marketplaces.
TOTAL ADDRESSABLE MARKET
2026 baseline
~$33.7B
2031 TRAJECTORY →
Year 5
~$76.7B
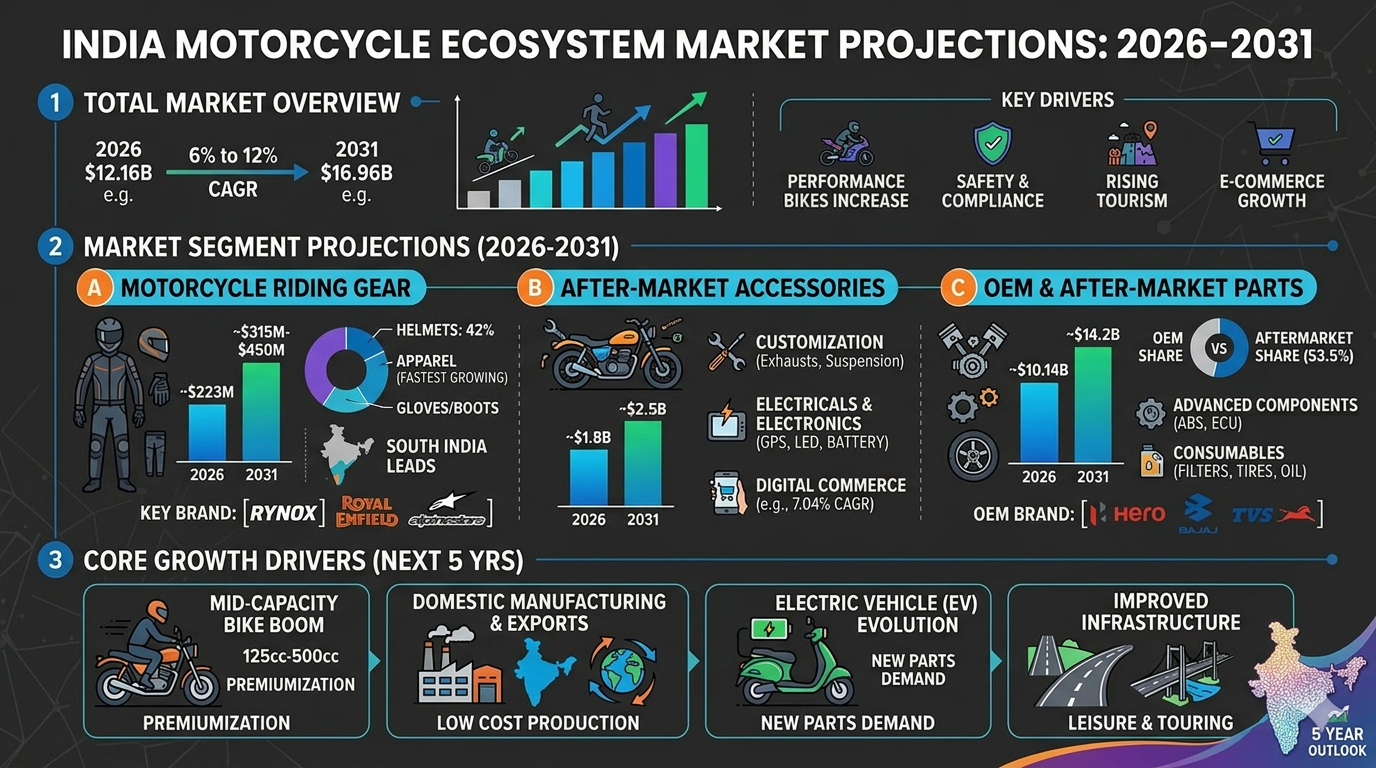
The 360° Ride Ecosystem.
'The Nykaa for Moto.'
We standardise moto-experiences through an AI-powered marketplace, then monetise the audience with gear, accessories, and OEM parts. A trust engine built on content and reviews lowers CAC and creates the 'Nykaa for Moto'.
Phase 1
The Marketplace of Moto-Experiences — The Hook
We standardise the chaos of moto-experiences using our proprietary AI engine. By offering a unified interface with clear dates, skill levels, information and pricing, we digitise partner inventory and establish immediate trust with the premium rider.
Phase 2 & 3
The 'Endless Aisle' — The Conversion
We monetise this captured audience via Agentic-e-commerce. By moving from Experiences to Gear/Aftermarket accessories (Phase 2) and OEM parts (Phase 3), we offer unlimited choice via direct-to-consumer fulfillment.
The Moat
The 'Trust Engine'
Uses AI and living content to capture traffic upstream, effectively lowering Customer Acquisition Cost (CAC) by 60%.
Community-Led.
Low-CAC. High-Conversion.
We launch by converting partner audiences and influencer communities into our first riders at near-zero CAC. Social commerce and curated stores turn earned reach into paid transactions.
01 / PARTNER SOCIAL LEVERAGE
Early in phase 1, we leverage our partners' social media presence to generate additional revenue. Even a 1% conversion of their overall followers gives us
30,000 riders
spending a minimum of ₹10,000 each over a year.
02 / SOCIAL COMMERCE
Influencers and experts open their stores on our platform, curate looks from our inventory across brands and promote the looks on their social channels — for a commission on total sale price.
The Trajectory To
1,335 Cr GMV.
The model scales from 10.75 Cr GMV in Year 1 to 1,335 Cr GMV in Year 5, while revenue grows 230x against 14x OPEX growth. Positive operating income is achieved by Year 3.
1,335 Cr
Total GMV by Year 5
284 Cr
Net Operating Income by Year 5
230x
Revenue growth vs 14x OPEX growth
7.5 Cr
Positive NOI achieved by Year 3
Growth is driven by evolving the primary revenue engine from high-margin Experiences in the early years to scalable E-Commerce (Gear and OEM parts). Built by riders with enterprise-scale corporate DNA — Myntra, Cult, ShareChat/Moj, ZEE5, Oddity Designs and GoodEarth.
The Model's
Load-Bearing Inputs.
Take-rates, MoM growth, and staged funding injections are the levers that drive the model. We keep physical operations at a constant 12% baseline while the platform takes a larger share of each transaction.
Revenue Mix Evolution.
Experiences → Commerce.
Early revenue is dominated by experiences—accommodation, schools, tours, and festivals—because they carry high margins and low logistics. By Year 3, gear and OEM parts become the majority drivers as e-commerce scales.
| Revenue Stream (GMV in Cr) | Y1 | Y2 | Y3 | Y4 | Y5 |
|---|---|---|---|---|---|
| Accommodation | 1.07 | 3.33 | 11.23 | 36.19 | 100.86 |
| Schools | 4.29 | 13.31 | 44.91 | 144.75 | 403.45 |
| Tours | 5.36 | 16.64 | 56.14 | 180.93 | 504.31 |
| Festival / Races | 0.01 | 0.20 | 0.76 | 2.14 | 6.00 |
| Custom Experiences | 0.02 | 0.40 | 1.52 | 4.28 | 12.00 |
| Gears (Commerce) | 0 | 0 | 17.06 | 72.88 | 154.21 |
| OEM Parts | 0 | 0 | 17.06 | 72.88 | 154.21 |
| Total GMV | 10.75 | 33.88 | 148.68 | 514.05 | 1,335.04 |
14x OPEX Growth,
Funding 230x Revenue Growth.
OPEX grows 14x from Year 1 to Year 5 while GMV grows 124x, demonstrating strong operating leverage. People, technology, and marketing are the largest cost centres, but stay proportionally controlled.
| Expense Department (Cr) | Y1 | Y2 | Y3 | Y4 | Y5 |
|---|---|---|---|---|---|
| People (HR / Salaries) | 1.60 | 2.62 | 5.09 | 8.01 | 16.89 |
| Technology | 1.28 | 2.05 | 4.07 | 6.41 | 13.51 |
| Marketing | 1.28 | 2.06 | 4.09 | 6.36 | 13.41 |
| Operations (Logistics) | 0.60 | 0.55 | 4.75 | 13.23 | 30.69 |
| Business Development | 1.28 | 2.05 | 4.07 | 6.41 | 13.51 |
| Legal & Compliance | 0.16 | 0.26 | 0.51 | 0.80 | 1.69 |
| Total OPEX | 6.20 | 9.59 | 22.58 | 41.22 | 89.70 |
From -4.58 Cr in Y1 to
284.11 Cr NOI by Y5.
Net platform revenue grows faster than costs, turning a -4.58 Cr NOI in Year 1 into 284.11 Cr by Year 5. Funding injections in Year 1, 3, and 5 maintain the cash runway for each growth phase.
| Metric (Cr) | Y1 | Y2 | Y3 | Y4 | Y5 |
|---|---|---|---|---|---|
| Net Platform Revenue | 1.62 | 5.08 | 30.08 | 128.51 | 373.81 |
| Total OPEX | -6.20 | -9.59 | -22.58 | -41.22 | -89.70 |
| Net Operating Income | -4.58 | -4.51 | 7.50 | 87.29 | 284.11 |
| Funding Injected | 12.5 | 0 | 40 | 0 | 80 |
| Ending Cash Balance | 7.94 | 4.52 | 67.59 | 172.94 | 621.42 |
TAM calculations derived from industry growth forecasts: Motorcycle Accessories (Global Market Insights / Transparency Market Research), Riding Gear & Apparel (Spherical Insights / Mordor Intelligence 2026-2031 Analysis), and Moto-Tourism (Technavio / IMARC Group).

The
Bottom
Line
Everything Motorcycling (em) is dismantling the friction of a broken, offline-first distribution model to build the 'Nykaa for Moto'.
We are capturing the high-LTV 'invested enthusiast' in a premium market growing at 36%.
VISION
Claim 1% of the $76Bn+ opportunity.
Join us for the ride.